Truck Loans Australia :: Articles

When should I use a personal loan?

What are the best situations to use a personal loan?

When should I use a personal loan?

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Unsecured personal loans can really help in a pinch. If your savings are low and your car breaks down, for example, such a loan can patch up your life. Or maybe you're buying a big-ticket item and you need backup money to cover a short-term hole in your bank account.
Unsecured personal loans are designed to be undertaken without the need to secure the loans against collateral, such as a property or a car. This makes unsecured personal loans ideal for people who do not own their own home and for people who have no other type of collateral to secure personal loans against.

Convenience

Part of their convenience is how quickly they can be approved - usually in one banking day, three tops.
Financial institutions don't care much about how you use an unsecured personal loan as long as you are a good candidate to pay it back.
The hitch is that because the borrower has no security, unsecured personal loans can be more expensive than secured loans.
These days, even the new crop of low-rate credit cards can often be cheaper than unsecured loans.
And besides interest, watch out for any annual service or maintenance fees on the loan that is either a flat fee or a percentage of the lump sum.
On the plus side, greater competition in personal loans from smaller financial institutions like the credit unions means there is a huge variation in the interest rates being charged - from 9 to 15 per cent.

Who qualifies?

Unsecured personal loans have a wider reach than secured personal loans. Both tenants and homeowners can take out unsecured loans, as well young people who have no verifiable personal credit history. Additionally, unlike secured personal loans, unsecured loans may also be open to people who have a poor credit record.
To successfully apply for a personal loan, the applicant for the loan must have a regular source of income. Proof of income from the unsecured loans applicant is likely to be requested by the personal loans companies and many lenders will also carry out background checks on other loans, secured or unsecured, that the personal loans applicant holds now or has held in the past.
Personal unsecured loans applicants who have been resident at the same personal address for more than three years, are married and have stable employment are those most likely to be successful in obtaining personal unsecured loans.
For homeowners, personal unsecured loans are ideal should the homeowner wish not to have personal loans officially secured against their property. The most successful applicants for unsecured loans in these cases are people who have equity in their property and no other unsecured loans. These factors above all else will help the homeowner applicant acquire unsecured loans, even if the homeowner has a bad personal credit history.
Loans companies offering unsecured borrowing in general do not limit what the funds from unsecured loans can be used for, so long as the person taking out the personal unsecured loans does not use the unsecured loans funds for illegal purposes.

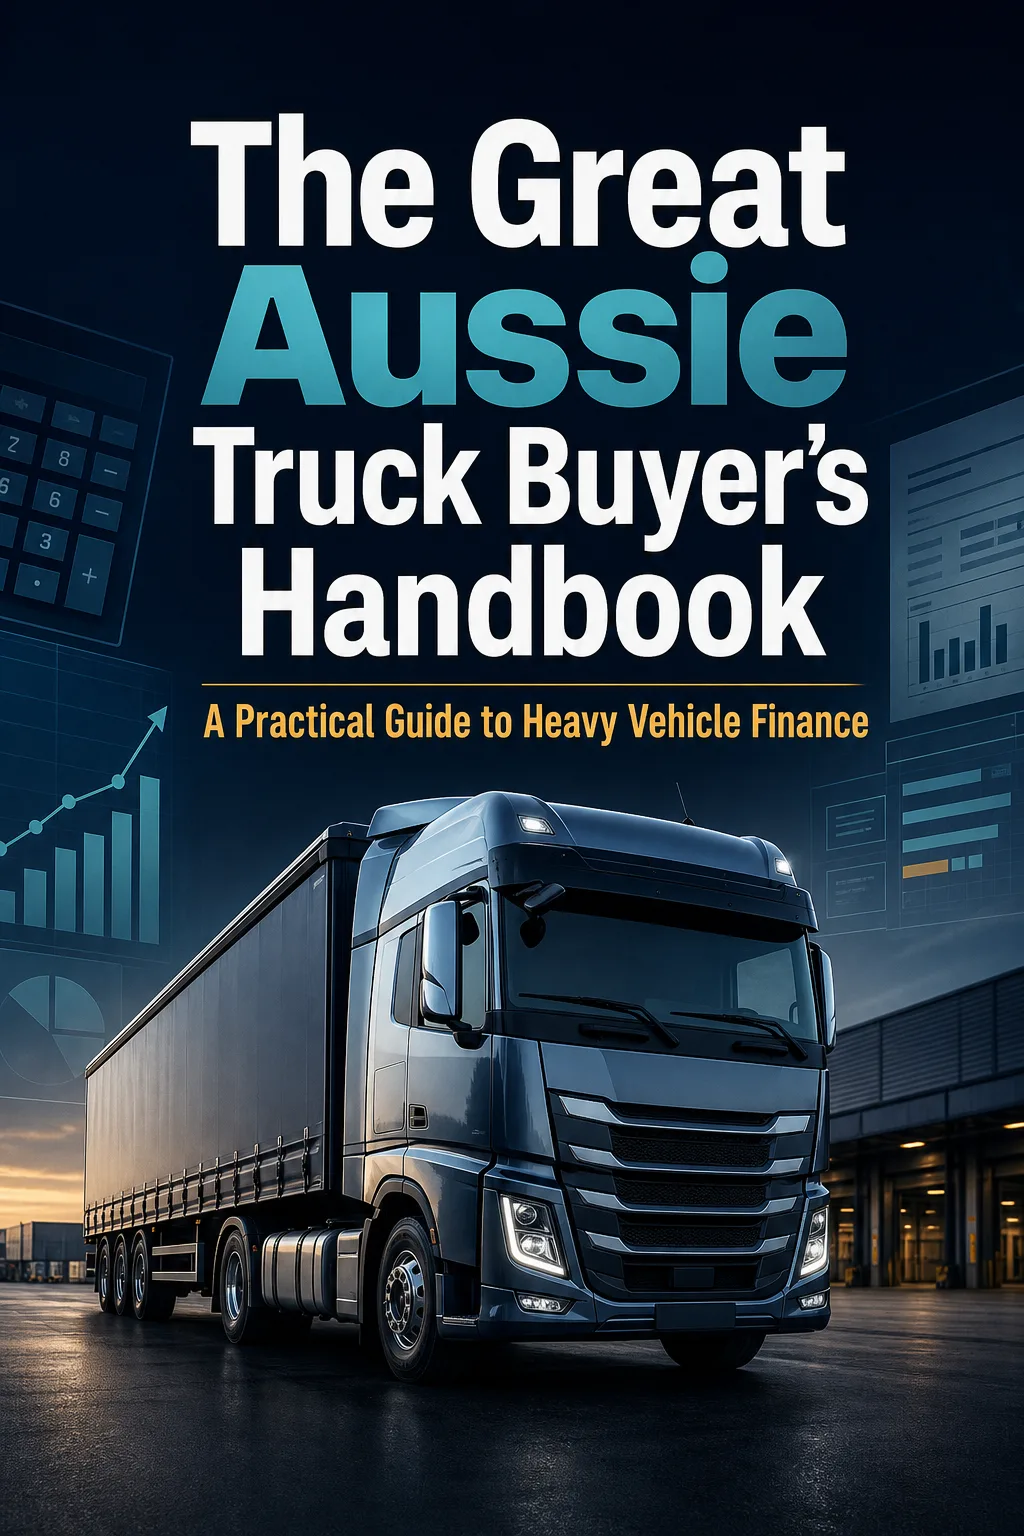
The Great Aussie Truck Buyer's Handbook: A Practical Guide to Heavy Vehicle Finance

The Great Aussie Truck Buyer's Handbook: A Practical Guide to Heavy Vehicle Finance image

Buying or financing a truck in Australia can affect more than the monthly repayment. The loan structure, fees, deposit, balloon payment, vehicle age and intended use can all shape cash flow and total borrowing cost. This practical guide is written for sole traders, tradies, logistics operators, fleet managers, small business owners and personal truck buyers comparing truck finance options. It explains commercial and personal truck loans, leases, chattel mortgages and hire purchase arrangements in clear, general terms. Inside, readers will find repayment factors, eligibility considerations, cost checklists, planning examples, case studies and questions to ask before making an informed finance enquiry.

Published: Sunday, 1st Aug 2021
Author: Paige Estritori

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Truck Loan Articles

Dealer Negotiations: Smart Tips for Australian Commercial Truck Buyers
Navigating the used truck market in Australia can be as complex as the rugged terrains these vehicles traverse. With the market growing steadily, the need for savvy bargaining and well-informed purchases has never been more critical. The significance of due diligence escalates when considering the investment at stake and the pivotal role these trucks play in driving businesses forward. - read more
Trucking Finance: How Leasing Can Support Business Growth
Truck leasing can help Australian trucking businesses access vehicles and equipment without the upfront cost of buying outright. This guide explains how leasing works, what to compare before signing, and how to manage leased trucks responsibly. - read more
Private Truck Loans in Australia: How They Differ from Commercial Truck Finance
Private truck loans can help individuals finance a truck for personal or non-business use, but they are assessed differently from commercial truck finance. This guide explains how private truck finance works in Australia, what lenders may consider, and how to compare it with business-purpose truck finance. - read more
Truck Finance for Sole Traders and Owner-Drivers in Australia
Sole traders and owner-drivers can access truck finance in Australia, but lenders may assess income, ABN history, contracts, cash flow and vehicle use differently from larger businesses. - read more
Commercial Truck Loan Approval with Limited Documents or Credit Issues
Limited paperwork, variable income or past credit issues can make a commercial truck loan application more complex, but they do not always rule out finance. This guide explains how lenders may assess low doc truck loans and bad credit truck loans, what evidence may help, and the risks to consider before applying. - read more

Finance News

RBA Rate Rise Puts Truck Loan Planning Back in the Spotlight
04 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent has made finance planning more important for Australian truck buyers. For sole traders, owner-drivers and fleet operators, the move does not automatically change every existing truck loan, but it can influence new lending, variable-rate facilities, refinance discussions and the way lenders test repayment capacity. - read more
Charging Access Becomes a Bigger Part of Electric Truck Funding
28 Oct 2026: Paige Estritori
Australia’s electric truck conversation has shifted from vehicle availability alone to the practical question of where, when and how commercial vehicles will charge. Ampol’s October 2026 activity has made that shift clearer, with the company announcing a proposed acquisition of Evie Networks and a separate memorandum of understanding with Foton Mobility Distribution to explore charging solutions for electric commercial vehicles. - read more
Why Emissions-Ready Trucks Are Changing Finance Decisions
16 Sep 2026: Paige Estritori
Australia’s truck market is moving deeper into an emissions-focused buying cycle, with more manufacturers promoting Euro 6-ready models, updated safety systems and more efficient drivetrains. For transport operators, tradies, delivery fleets and owner-drivers, this is not just a technology story. It is a finance planning issue that can affect purchase timing, loan structure and the total cost of keeping a vehicle productive. - read more
A Cooler Truck Market Is Changing How Operators Finance Their Next Vehicle
02 Sep 2026: Paige Estritori
Australia’s truck market appears to be settling into a more cautious rhythm after the stronger buying bursts seen around tax-time and major model changeovers. The latest industry sales commentary points to a market where operators are still replacing essential vehicles, but many are taking longer to commit, weighing up utilisation, operating costs and finance structure before signing off on a purchase. - read more
Why Faster Finance Assessments Still Need Strong Truck Loan Preparation
26 Aug 2026: Paige Estritori
Australia’s business lending market is moving further towards faster digital assessment, with banks and non-bank financiers continuing to invest in automated credit checks, electronic document handling and data-led serviceability reviews. For truck buyers, the direction is encouraging: finance applications can be assessed more efficiently than the traditional paper-heavy process many operators remember. - read more

Knowledgebase
Inflation:
The rate at which the general level of prices for goods and services rises, eroding purchasing power.